
On this page
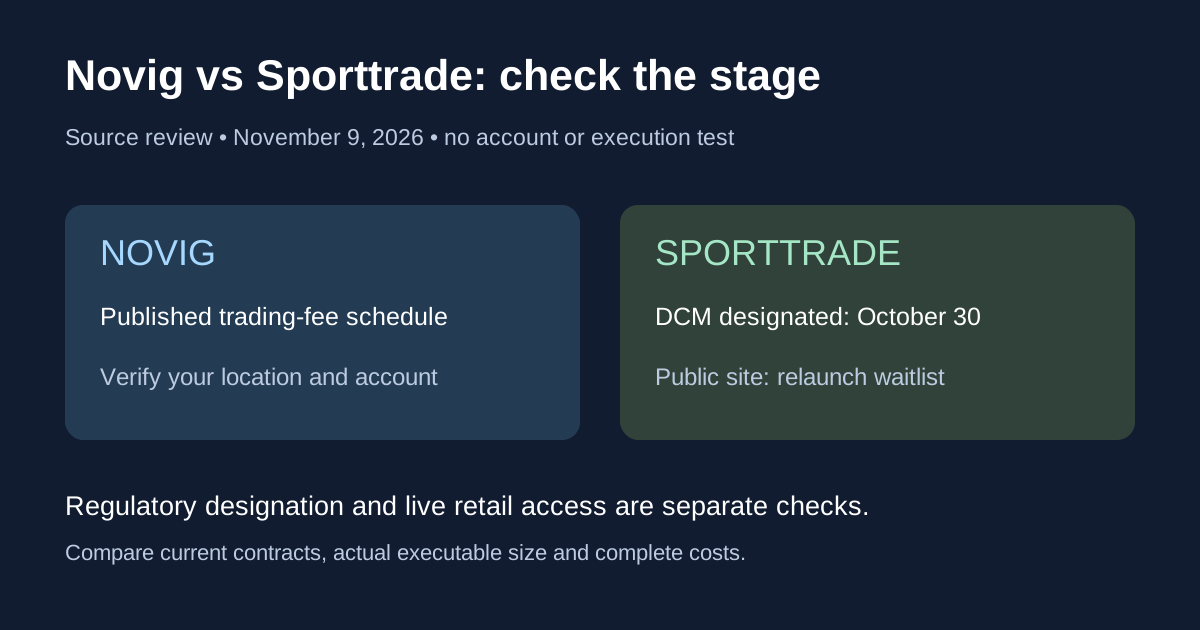
Novig vs Sporttrade is currently a comparison between different publicly documented product stages. Novig publishes a trading-fee schedule for its current exchange product. Sporttrade’s public website presents a relaunch waitlist, while the CFTC lists Sporttrade DCM LLC as a designated contract market.
Checked November 9, 2026. This guide compares official records and adds original arithmetic. We did not open accounts, deposit funds or execute trades. A regulatory milestone and a working retail account are separate things to verify.
Novig vs Sporttrade: the current comparison
| Question | Novig | Sporttrade |
|---|---|---|
| What does the public product evidence show? | Published current trading-fee rules | Public site says it is re-entering the market soon and offers a waitlist |
| What regulatory record is relevant here? | Ludlow Exchange, LLC: designated June 16, 2026 | Sporttrade DCM LLC: designated October 30, 2026 |
| Can this guide establish your account access? | No; check current account and location requirements | No; designation and waitlist do not establish retail access |
| Can we compare current executed costs? | We can illustrate its published fee formula | No current retail fee and execution evidence is established here |
We do not select a universal winner from those facts. A useful comparison must first establish that the products and account routes being compared are actually available to the reader.
Sporttrade is designated, but its public site still presents a waitlist
The CFTC’s Sporttrade DCM record shows Designated status dated October 30, 2026. Calling that record merely a pending application would be outdated.
Separately, Sporttrade’s public website says it is re-entering the market soon and invites users to a waitlist, including interest in future API access. This establishes what the public site presents; it does not establish a completed retail launch, a customer’s permissions or an executable market.
These facts are compatible. A designation can precede a particular public launch or account-access route. If you see a screenshot of a sports order book on a marketing page, do not assume it is a live quote available to your account.
Why older Sporttrade state lists need context
A 2026 New Jersey Division of Gaming Enforcement order records that Fliff’s acquisition closed around May 29 and that Sporttrade advised the Division it had ceased serving the New Jersey casino industry. The order revoked specified transactional waivers and set conditions for recommencing that business.
That is a New Jersey record concerning the named entity and waivers. It should not be stretched into a universal statement about every state or every later federal product. Conversely, an older help page listing state sportsbook access is insufficient proof of present availability after a corporate or regulatory change.
Use a dated sequence: identify the old product, the later change, the current regulatory record and the present public access route. Do not collapse those into a single timeless “legal states” list.
What the Novig record establishes
The CFTC record for Ludlow Exchange, LLC shows Designated status dated June 16, 2026. Our Novig overview explains the current event-contract model and its relationship to older product descriptions.
A designation does not establish a profitable trade or guarantee that a displayed price will fill. For account access, use the current requirements addressed in our Novig availability guide and confirm the policy shown by the venue for your actual location.
Novig fees depend on the trade type and fill
Novig’s official fee schedule distinguishes makers and takers. It lists no maker trading fee and no pre-game straight trading fee. Its live-straight and applicable futures taker formula uses 0.06 ×P ×(1−P) per contract. Golf and tennis futures are listed as exceptions to the futures trading fee as of September 10, 2026.
The schedule treats app/web parlay taker fees differently: the coefficient is 0.10 and the fee is already included in the quoted price. Do not add that included fee a second time. Check the exact market, interface and actual fill role rather than treating every order as the same transaction.
This is a dated summary of trading charges, not an assertion that every account activity or payment method is free. Keep funding, withdrawal and other charges separate when applicable.
Original live-straight example at 40¢
Assume 125 hypothetical contracts execute as taker fills in a market subject to Novig’s live-straight coefficient. Each costs $0.40 before the fee and pays $1 if the selected outcome wins. Assume no other charges or credits.
| Item | Calculation | Amount |
|---|---|---|
| Contract purchase outlay | 125 ×$0.40 | $50.00 |
| Trading fee | 0.06 ×0.40 ×0.60 ×125 | $1.80 |
| Total entry outlay | $50.00 +$1.80 | $51.80 |
| Winning settlement under the assumption | 125 ×$1 | $125.00 |
| Winning net result before excluded items | $125.00 −$51.80 | $73.20 |
The fee is $0.0144 per contract. The total outlay per contract is $0.4144. That is 41.44% of the stipulated $1 payout, compared with the 40% raw contract price.
The $1.80 fee is 3.6% of the $50 purchase outlay, while the per-contract outlay increase is 1.44 percentage points of the $1 payout. These use different denominators. Calling the increase simply “1.44%” without naming the reference can mislead.
All prices and quantities are invented. This is not a live offer, a performance result or a Sporttrade fee comparison. A losing $0 settlement loses the assumed $51.80 entry outlay. An early exit introduces separate execution and cost questions.
How to compare when one fee schedule is unverified
Leave Sporttrade’s current retail fee field unknown in this comparison. Do not put zero there or import an old sportsbook commission into a prospective event-contract product.
For a future like-for-like comparison, first obtain the current contract rules, account route, fee schedule, executable price and quantity at a common observation time. Calculate the full entry outlay for each route. If the underlying settlement conditions differ, explain that difference before ranking prices.
Even identical headline fees can lead to different costs when depth differs. Our market-microstructure guide illustrates why a small best quote may not cover the whole order. The implementation-shortfall guide explains the effect of partial execution.
A practical Novig–Sporttrade comparison checklist
- Identify the product and legal entity. Do not assume an old app and a newly designated exchange have identical terms.
- Confirm actual access. Separate public information, waitlist registration and an approved trading account.
- Match the contract. Compare outcome definitions, market rules, deadlines and settlement sources.
- Collect executable evidence. Record price, size, time and fill assumptions.
- Separate costs. Identify trading fees, included charges, payment charges and any contingent credits.
- Preserve unknowns. Missing evidence is a reason to qualify the comparison, not an invitation to invent a number.
For event research, use Alphascope market news. Keep a dated record of venue access and execution terms alongside the underlying sports thesis. Neither a registration record nor a comparison article proves that a specific account can place a trade.